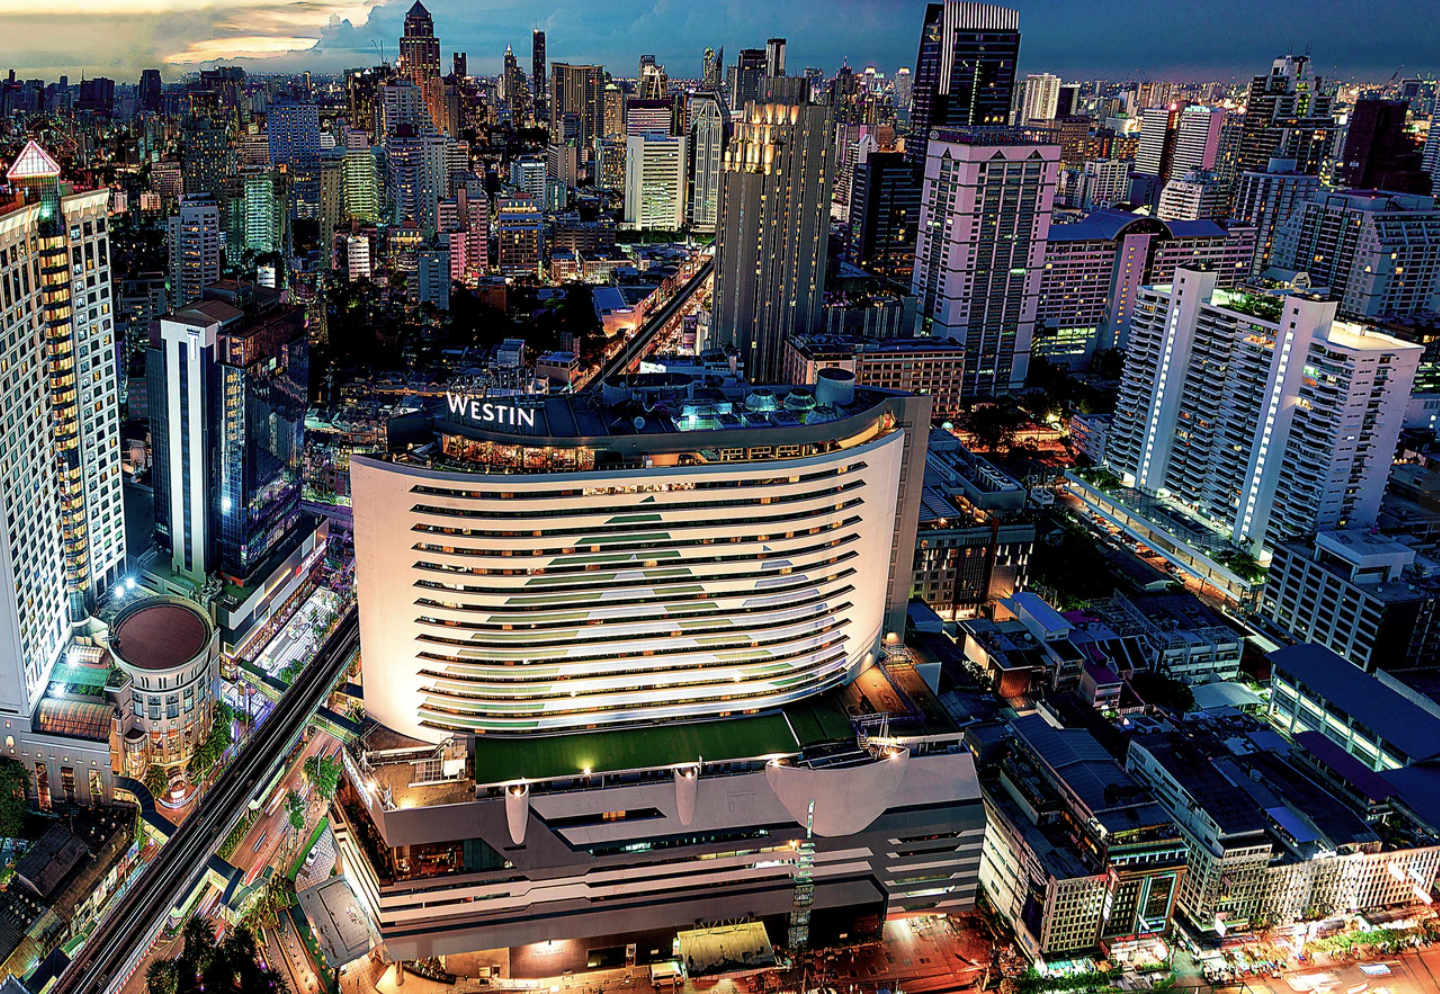
At first glance, the proposed transaction involving The Westin Grande Sukhumvit Bangkok looks extraordinary.
Grande Asset Hotels and Property (GRAND) has announced the proposed transfer of the hotel business and related assets to Rabbit Holdings, or its nominee, for consideration of up to ฿494.6 million. With 362 rooms, the simple arithmetic produces a figure of approximately ฿1.37 million per key.
For an internationally branded hotel at one of Bangkok’s most valuable intersections — Sukhumvit and Asoke — that number looks almost unbelievable.
And it is.
Because ฿1.37 million per key is not really what this transaction is telling us.
The land structure
A closer examination of the land underneath the Westin explains why.
The hotel and Robinson retail complex occupy approximately 5 rai 15 square wah, or around 8,060 square metres, but GRAND does not own the principal site outright. The core parcel is held under an undivided co-ownership structure, with one landowner group holding 75% and another holding 25%. There is also a separate 13-square-wah access parcel.
Importantly, the 75%/25% split does not represent neatly divided physical sections of the property. They are fractional ownership interests across the same underlying parcel.
The original ground lease was executed in 1988, registered in 1992 and ran for 30 years until April 2022. What happened after that has ultimately become more important to the future of the Westin than its occupancy, ADR or even its brand.
The two landowner groups subsequently moved down very different paths.
The owners representing 75% of the land had initially been the more cooperative side, with GRAND negotiating an extension of the lease. But as GRAND’s liquidity deteriorated, rent and other contractual payments fell into arrears. That group eventually terminated the lease and demanded that GRAND remove the hotel structure, clear the land and evict subtenants, including Robinson.
The remaining 25% interest became the subject of a separate legal dispute. Negotiations over lease renewal and land terms broke down, a substantial deposit was forfeited, and the dispute moved into the courts. The first-instance court ruled in favour of the landowners, while GRAND appealed.
The analysis below is based on GRAND’s public disclosures and publicly available transaction information.
So by 2026, GRAND found itself in an extraordinary position: it had a 362-room Westin, an established Marriott-managed operation and one of Bangkok’s strongest hotel locations, but it no longer had a secure and unified land position underneath the building.
The real economic cost
That is where Rabbit’s proposed transaction becomes particularly interesting.
This is not simply a case of Rabbit paying ฿494.6 million and acquiring a hotel. The proposed restructuring appears to solve the two pieces of land in two completely different ways.
On the 25% side, Rabbit or its nominated entity would acquire the freehold interest directly from that landowner group. On the 75% side, the intention is to settle outstanding lease liabilities and establish a completely new 30-year registered ground lease with Rabbit.
If completed on those terms, Rabbit would therefore become owner of 25% of the underlying land while holding a long-term lease over the remaining 75%.
That is a far more useful way of understanding this deal than dividing ฿494.6 million by 362 rooms.
Rabbit is not really buying 362 hotel rooms at ฿1.37 million each. It is attempting to reconstruct control of the real estate beneath them.
The true investment cost therefore lies in the price paid for the 25% freehold interest, the economics of the new 30-year lease over the remaining land, settlement of arrears and compensation, future rent escalation and whatever capital expenditure may ultimately be required at the hotel.
Until those numbers are known, we do not know Rabbit’s true economic cost per key.
And that leads to the wider investment lesson.
The Westin has almost everything hotel investors normally look for: international branding, scale, direct BTS/MRT accessibility, a substantial retail component and a location at the heart of Bangkok’s Sukhumvit commercial corridor.
Yet none of those things eliminates land risk.
A successful hotel can sit above a fragile property structure. A strong brand cannot cure a broken lease, and an attractive EBITDA cannot compensate for losing the legal right to occupy the land beneath the building.
The wider portfolio context
The story also needs to be viewed against GRAND’s broader financial position.
In October 2024, GRAND sold the Hyatt Regency Bangkok Sukhumvit and The Allez Mall for approximately ฿5.06 billion, in what was hailed to be the largest single asset hotel transaction in Thailand with a large proportion of the proceeds directed toward bank debt and debenture repayments.
Royal Orchid Sheraton presents another challenge. Its real estate had previously been monetised through a REIT structure carrying a future repurchase obligation, and that repurchase was not completed on the original July 2026 deadline.
Now the Westin is being restructured.
Taken together, these transactions raise a much broader question about the difference between owning good assets and having a balance sheet strong enough to keep them.
There is also a final twist.
BTS Group owns 18.2% of GRAND, while Rabbit Holdings sits within the BTS group. Rabbit is therefore not arriving as an entirely unrelated third-party hotel investor.
The transaction also illustrates how the interests of a significant shareholder and those of the listed company can intersect when an asset requires substantial restructuring and fresh capital.
That may ultimately prove to be the most interesting part of the transaction.
So, is The Westin Grande Sukhumvit changing hands at ฿1.37 million per key?
Not really.
The real transaction is about who controls the land, for how long, and at what total economic cost.
For those of us involved in hotel investment, perhaps that is the more useful question this transaction raises:
When evaluating a leasehold hotel, how much weight should we place on the building and operating performance — and how much on the security of the land beneath it?
#HotelInvestment #BangkokHotels #HospitalityRealEstate #ThailandRealEstate #HotelTransactions
Leave a Reply